Find coverage built to withstand your toughest risks.
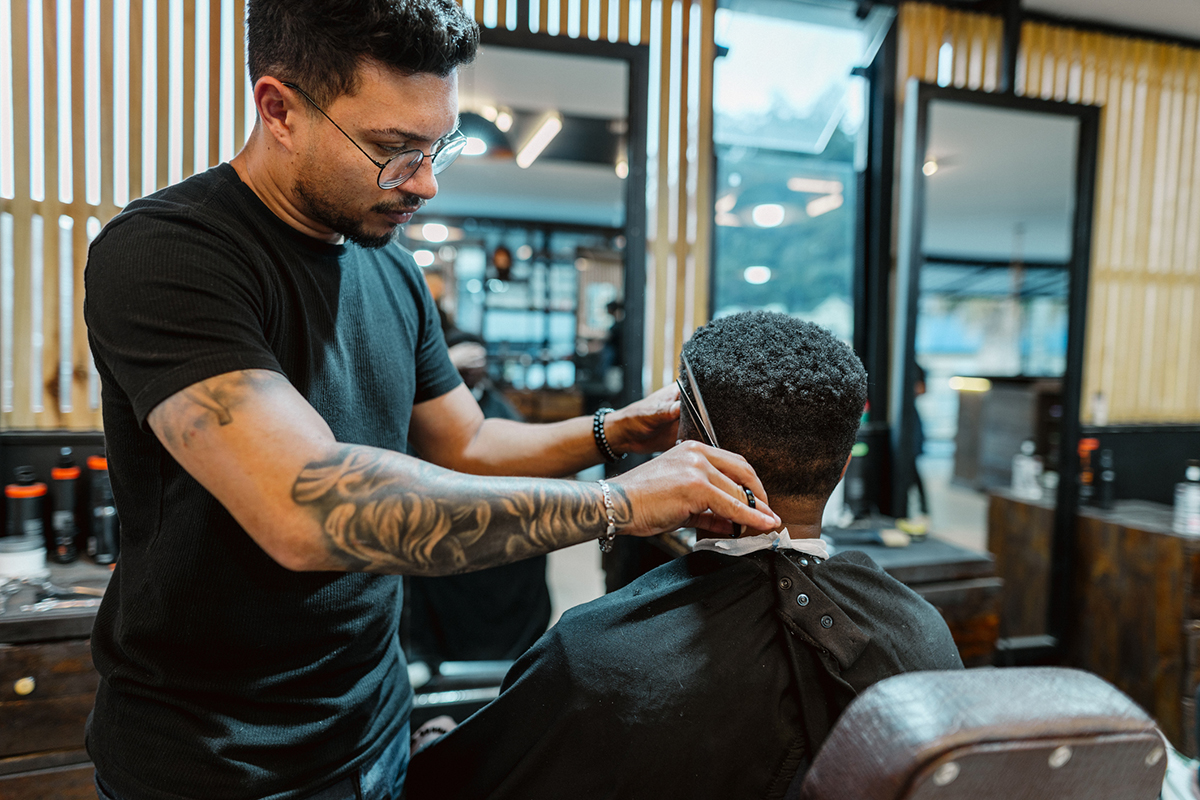
Personal services and wellness businesses need insurance because the work is hands-on, clients come and go throughout the day, and equipment is used from appointment to appointment. Standing for hours, working up close with clients, and repetitive movements are all part of the job, and when something goes wrong, coverage protects your business and employees so the schedule keeps moving.
Most personal services and wellness businesses need workers’ compensation, general liability and a business owner’s policy (BOP). Together they protect your team, your clients and your equipment.
Workers' compensation
If a stylist strains their wrist after a long day of cutting or a massage therapist tweaks a shoulder, workers’ compensation pays for medical care and part of their lost wages. It also protects you if an injured employee files a lawsuit. If you have staff, it’s most likely a policy you need in place before the first appointment.
Business owner's policy
A BOP bundles general liability, property and business interruption coverage into a single policy. After a covered loss like a fire, it can help pay to repair or replace salon chairs, massage tables, fitness equipment and other business property and replace income while you reopen.
General liability insurance
General liability covers injuries and property damage your business may cause to someone else. If a client slips on a wet floor near the shampoo sinks, it can help with their medical bills, legal costs and settlements, depending on your policy terms.
*Coverage needs vary by business — this reflects commonly needed lines, not a complete list of every policy your business may require.
How much does insurance cost for
Personal service and wellness
businesses?
Personal services and wellness insurance costs depend on:
- Payroll and number of employees
- Type of business and services you offer
- Value of your equipment
- Your location and state
- Your claims history
- Coverage limits and deductibles
Personal services and wellness business insurance costs vary, but EverPeak policies start at $18 a month.
What makes EverPeak different from other insurance carriers?
Why choose EverPeak for workers’ compensation coverage?


FAQs
In many states, businesses with employees are required to carry workers' compensation insurance. Other coverage, like general liability, is often required by landlords or client contracts rather than by state law, so requirements vary by state and industry — it's worth confirming your specific obligations.
Often, yes. A business owner's policy (BOP), for example, can bundle property and liability coverage under one plan. Higher-risk or more specialized trades may need additional standalone coverage layered on top, depending on how they operate.
Reach out to our customer service team directly at 833.929.0523, or fill out our contact form, and we’ll point you in the right direction.
Cost depends on your industry, business size, payroll and claims history. Connect with an agent for a quote based on your specific business.
General liability covers third-party bodily injury and property damage claims — a customer's slip and fall in your store, or accidental damage caused by your work. It typically pays for medical expenses, legal defense costs and damages if your business is found responsible.

Ready for insurance that works as hard as your business?
We’ll help you secure the coverage you need.